
How GMC Buick Financing Works for Bad Credit in Indian Trail
A clear guide to GMC and Buick financing for bad credit in Indian Trail, NC in 2026 — how approvals work, what to bring, and what to expect from local dealers.
If your credit score is holding you back from a truck or SUV you actually need, you're not alone — and you're not out of options. Bad-credit auto financing is one of the most common questions we hear from shoppers across Indian Trail, NC, especially from families commuting up US-74 toward Charlotte or working trades where a dependable GMC Sierra isn't a luxury, it's a work tool. The good news: financing a GMC or Buick with less-than-perfect credit is genuinely possible in 2026, and understanding how the process works locally will save you time, money, and frustration.
What Counts as "Bad Credit" When Financing a GMC or Buick?
Auto lenders generally group credit into tiers. Auto lenders group credit into tiers — prime, near-prime, and subprime — with subprime borrowers generally facing higher rates and stricter terms. Deep subprime borrowers, those with the lowest scores, face the tightest financing conditions. If you're anywhere in the subprime range, you can still qualify for a GMC Sierra, Terrain, Acadia, or a Buick Encore GX. You'll just see different terms: higher rates, larger down payments, or shorter loan lengths.
The key thing to understand is that credit score is only one factor. Lenders working with dealerships also weigh your income stability, debt-to-income ratio, how long you've been at your job, and how much money you can put down. A 580 score with a steady paycheck from a job in the Sun Valley or Porter Ridge area can look very different to a lender than a 580 with recent job changes.
How Bad-Credit Financing Actually Works at a Dealership
When you apply for financing through a dealer rather than a single bank, your application is typically submitted to a network of lenders — captive lenders like GM Financial, regional banks, credit unions, and specialty subprime lenders. Each lender reviews your profile and, if approved, offers terms. The dealer's finance team then presents you with the options that came back.
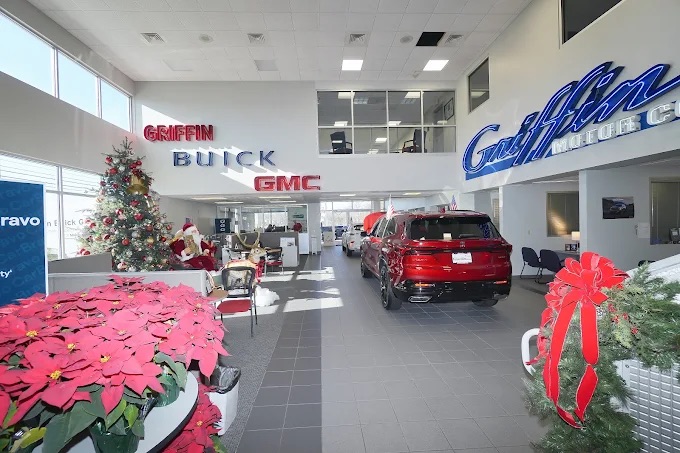
For buyers with bruised credit, this multi-lender approach matters. A single bank might decline you outright, while a subprime specialist might approve you with reasonable terms on the same vehicle. That's why working with a full-service GMC Buick dealership near you often produces better results than applying at your primary bank first. Griffin Buick GMC works with GM Financial and a network of lending partners to offer financing, which means your application reaches multiple sources at once.
What You'll Typically Need to Bring
- A valid North Carolina driver's license
- Recent pay stubs (usually the last 30 days) or proof of income if self-employed
- Proof of residence — a utility bill or lease agreement showing your Indian Trail, Stallings, or Union County address
- Proof of insurance
- References — many subprime lenders request a list of personal references
- Down payment funds — subprime approvals often require a meaningful down payment (contact Griffin Buick GMC for current guidance on amounts)
North Carolina Rules That Affect Your Loan
A few things about buying a vehicle in North Carolina are worth knowing before you sign. North Carolina charges a Highway Use Tax on vehicle purchases rather than the standard state sales tax — check with the dealership or NCDMV for the current rate and how trade-in credit affects the calculation. Registration and title work is handled through the NCDMV, and Union County residents typically complete this at a local tag office rather than at the dealership counter, though most dealers will process the paperwork on your behalf.
North Carolina also does not have a general cooling-off period for vehicle purchases — once you sign, the deal is binding — so it's worth reviewing your buyer's order carefully before you initial anything. If a lender requires a co-signer, that person's credit and income are legally tied to the loan.
Practical Ways to Improve Your Approval Odds
If you're planning to shop for a Sierra 1500, a Terrain, or a CarBravo certified pre-owned Buick in the next 30–90 days, a few moves can meaningfully improve the terms you're offered:
- Pull your credit reports first. You're entitled to free reports from each of the three bureaus. Dispute any errors before you apply.
- Save a real down payment. Even a modest amount down changes how lenders view the risk. On a subprime loan, a stronger down payment can improve your rate — contact Griffin Buick GMC to discuss current expectations.
- Bring a trade-in. Positive equity in your current vehicle functions the same as cash down. Griffin Buick GMC will appraise your trade at no cost, and customers have consistently noted fair trade-in values in Google reviews — as one reviewer wrote, "The dealership offered an advantageous trade-in value for my existing vehicle."
- Stabilize before you apply. Lenders generally like to see a consistent period of time at the same job and residence. If you're mid-move or mid-job-change, waiting a few weeks can matter.
- Consider a CarBravo certified pre-owned GMC or Buick. CarBravo vehicles at Griffin Buick GMC come with GM-backed warranty coverage, and financing terms on certified pre-owned inventory are often more favorable than on non-certified used vehicles.
Why a Local Dealer Often Beats an Online-Only Lender
Online car-buying platforms can get you a pre-approval quickly, but they lock you into their inventory partners and their rate. A local GMC dealer with a broad lender network can shop the same application to multiple sources at once — and, importantly, can pair the financing conversation with the actual vehicle conversation. That matters because the vehicle you choose (new vs. used, sedan vs. truck, mileage, model year) affects which lenders will approve and at what rate.
Buyers in Indian Trail often ask where the best place to buy a GMC Sierra near them is when credit is a concern. Our honest answer: choose a dealership that has a dedicated finance team, works with multiple subprime lenders, and will walk you through the numbers without pressure. Griffin Buick GMC is a family-owned dealership that has served the community since 1946, and its finance team's approachability comes through in reviews — one customer noted that the finance staff were "polite and easy to talk with." Griffin Buick GMC also states it never uses addendums or surprise fees, so the numbers you review are the numbers you sign. The dealership holds a 4.6-star rating from 1,321 Google reviews as of May 2026, with repeat customers and fair trade values among the most frequently cited reasons for returning.
Frequently Asked Questions
Can I get approved for a GMC Sierra with a 550 credit score?
Yes, approvals in the 500–580 range happen regularly, though you should expect a higher rate and a down payment requirement. The specific terms depend on your income, the vehicle you choose, and which lenders in the dealer's network respond.
Will applying for financing hurt my credit score?
When a dealer submits your application to multiple lenders within a short window, the credit bureaus typically treat those inquiries as a single event for scoring purposes. The score impact is usually small and short-lived.
Do I need a co-signer to finance a Buick with bad credit?
Not always. Many subprime approvals go through without a co-signer if your income and down payment are strong enough. A co-signer can help lower your rate or expand your budget, but it isn't a requirement in every case.
How long does bad-credit financing take to finalize?
Most approvals come back within a few hours during normal business hours. If additional documentation is requested — pay stubs, proof of residence, references — the process can extend to a day or two.
Can I refinance later once my credit improves?
Yes, and many buyers do. If you make on-time payments and your score improves over time, refinancing to a lower rate is a common next step.
Does Griffin Buick GMC offer any protection products that make sense for a subprime buyer?
Yes. Griffin Buick GMC offers First Mile Protection Products including GAP coverage, Vehicle Service Contracts, and Prepaid Maintenance Plans — options that can be especially valuable when you're financing at a higher rate and want to protect your investment. Ask the finance team which products make sense for your specific loan structure.
Can I shop for a car at Griffin Buick GMC if English isn't my first language?
Yes. Griffin Buick GMC's website is available in Spanish, and the dealership serves a broad community across Indian Trail, Monroe, Waxhaw, Fort Mill, and Rock Hill. If language has been a barrier to exploring financing options in the past, that shouldn't stop you from starting a conversation with the team.
Bringing It All Together
Bad credit doesn't have to mean bad options. With the right documentation, a realistic down payment, and a dealer willing to work multiple lenders on your behalf, financing a GMC or Buick in Indian Trail is a workable path — even if past credit issues have made you cautious about walking into a showroom. Shoppers in Union County who want to explore what they'd actually qualify for can reach Griffin Buick GMC at https://www.griffinmonroe.com/ or by calling (704) 288-0210 to start a no-obligation credit application and inventory conversation.