
How GMC Certified Pre-Owned Financing Works in Monroe, NC
A clear walkthrough of GMC CPO financing for Monroe, NC buyers — eligibility, rate tiers, mileage caps, GM Financial rules, and how to prepare.
GMC Certified Pre-Owned (CPO) financing in Monroe, NC works like a standard auto loan with one important twist: because the vehicle has passed GM's factory certification, lenders — especially GM Financial — often offer more favorable terms than on a standard used car. That typically means access to lower rate tiers, longer term options, and stricter mileage and age caps than ordinary used financing. You apply through the dealer, your credit tier determines your rate band, and the car's certified status unlocks programs a non-certified used vehicle wouldn't qualify for.
If you're shopping a certified pre-owned GMC near Monroe, that distinction matters at the signing table. Below is how the process actually unfolds, what rules apply, and what to prepare before you walk in.
What makes GMC CPO financing different from a regular used loan?
GMC CPO financing is used-vehicle financing on a vehicle that has passed GM's multi-point inspection, falls within GM's age and mileage limits, and carries a factory-backed limited powertrain warranty. Because of that certification, GM Financial and partner lenders will often approve longer terms and offer rate tiers closer to new-car financing rather than standard used rates.
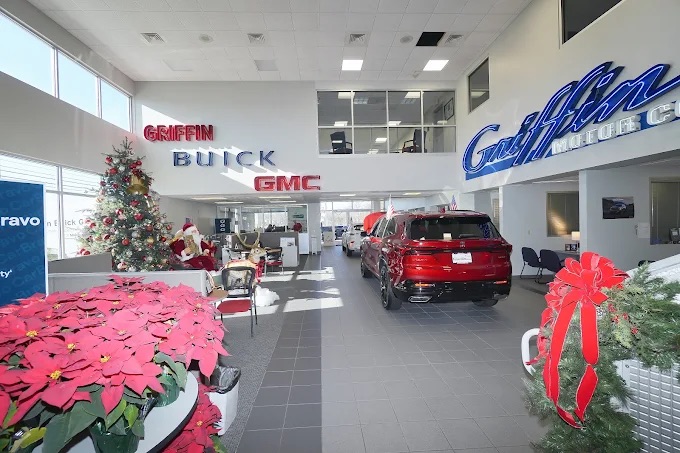
In practical terms, a non-certified used truck and a certified one at similar prices can carry noticeably different APR offers, because the lender sees less residual risk on the CPO unit. Griffin Buick GMC — a family-owned dealership that has served the Monroe area since 1946 — works with GM Financial and a network of lending partners, which is the same channel through which CPO-specific programs flow.
Which GMC vehicles actually qualify as CPO?
To qualify for GMC CPO status, a vehicle generally must fall within GM's age and mileage limits, pass GM's multi-point inspection, and have a clean title history. Vehicles outside those limits can still be financed, but not as CPO — meaning you'd lose access to the CPO rate programs and warranty extension.
This is where sticker shopping gets tricky. Griffin Buick GMC carries CarBravo certified pre-owned vehicles alongside its new Buick and GMC inventory, which gives Monroe buyers both the GMC CPO path and a broader certified used selection to compare.
How do credit tiers and rate bands work on a CPO GMC?
GM Financial sorts applicants into credit tiers — typically labeled roughly from top-tier (highest credit) down through subprime bands. Your tier determines the rate band you qualify for, the maximum term available, and the loan-to-value ratio the lender will advance. A top-tier buyer on a CPO Sierra can usually access the longest terms and the lowest published rates; a mid-tier buyer sees a higher rate and often a shorter maximum term.
Rate figures change constantly and are tied to current GM Financial programs, so published numbers go stale within weeks. For current CPO rate programs on specific models, check the specials page at griffinmonroe.com or ask the finance desk directly rather than relying on third-party rate screenshots.
What are the mileage and age caps that affect financing terms?
GM Financial generally caps CPO loan terms based on the vehicle's age and odometer reading at origination. Newer, lower-mileage CPO units can typically be financed for longer terms; higher-mileage certified units are capped shorter. The combined age-plus-term rule — the vehicle's age in years plus the loan term in years — is a common underwriting ceiling that limits how far you can stretch payments on an older CPO truck or SUV.
This matters because stretching a loan to lower the monthly payment doesn't always work on an older CPO vehicle — the lender simply won't approve the term.
How does the application process work at a Monroe dealership?
You apply through the dealer's finance office, which submits your application to GM Financial and, in parallel, to its network of lending partners. The dealer compares the offers that come back and presents the strongest combination of rate and term for your situation. You can also arrive with your own pre-approval from a bank or credit union and let the dealer try to beat it.
For Monroe, NC buyers, the practical sequence looks like this:
- Pull your own credit report and know your score before you shop.
- Gather pay stubs, proof of residence, and your driver's license.
- Decide your target monthly payment and maximum term before you negotiate.
- Submit the credit application — typically a single application feeds multiple lenders.
- Review the offers, including CPO-specific rate programs, before signing.
North Carolina charges a vehicle titling tax on purchases rather than standard sales tax, and that figure gets rolled into most financed deals — budget for it when you compare out-the-door numbers.
How do CPO prices in Monroe compare to new GMC pricing?
CPO pricing varies by model year, mileage, trim, and local market demand around Monroe and the broader Charlotte metro, so there's no single "CPO price" to publish. The useful comparison is against new MSRP, since the CPO discount versus new is what justifies the slightly higher rate band compared to new-vehicle financing.
| New GMC Model (2026) | Starting MSRP | Typical CPO Candidate |
|---|---|---|
| the 2026 GMC Terrain, starting at $30,200 (as of October 2026) | Starting MSRP shown | 2022–2024 Terrain |
| the 2026 GMC Acadia, starting at $43,800 (as of October 2026) | Starting MSRP shown | 2022–2024 Acadia |
| the 2026 GMC Sierra 1500, starting at $38,300 (as of October 2026) | Starting MSRP shown | 2022–2024 Sierra 1500 |
| the 2026 GMC Yukon, starting at $69,600 (as of October 2026) | Starting MSRP shown | 2022–2024 Yukon |
For live CPO inventory and prices, contact Griffin Buick GMC — a stocked unit's actual asking price is the only figure that matters for your deal.
What should Monroe, NC buyers prepare before applying?
Monroe buyers should walk in with a current credit score, two recent pay stubs, proof of residence (a utility bill works), a valid NC driver's license, and current insurance information. If you're trading in, bring the title or payoff information and both sets of keys. Having these ready lets the finance office submit a complete application on the first pass.
A customer's recent experience illustrates how the process goes when it's handled cleanly:
Griffin had the truck I wanted. My sales person Miguel was very professional and easy to talk with. After I drove 40 miles to view the truck, Miguel had it pulled up and ready to go for my test drive. I had a couple of special requests which they honoured without batting an eye such as looking at the truck up in the air so I could see the underside of it and being very competitive with the interest rate for my financing. It was a great buying experience and I would recommend this dealership to anyone looking for a fair deal with great vehicles.
Frequently asked questions
Can I get GMC CPO financing with average credit in Monroe, NC?
Yes. GM Financial and partner lenders approve CPO loans across most credit tiers, though the rate and maximum term depend on your score. Average-credit buyers typically land in a mid-tier rate band with a shorter maximum term than top-tier applicants. Bringing a larger down payment or a creditworthy co-signer can shift you into a better tier.
Does a CPO GMC come with a warranty that transfers if I refinance?
Yes. The GMC CPO warranty is tied to the vehicle, not the loan, so refinancing with a different lender does not void coverage. The factory-backed limited powertrain warranty and included inspection coverage follow the VIN. Keep your CPO documentation with the vehicle records in case a future owner or servicer needs to verify eligibility.
How long can I finance a certified pre-owned GMC?
Loan terms for GMC CPO vehicles vary depending on the vehicle's age, mileage, and your credit tier, with newer, lower-mileage units qualifying for the longest terms. Newer, lower-mileage CPO units qualify for the longest terms. Older or higher-mileage certified vehicles are capped shorter because of GM Financial's combined age-plus-term underwriting limits.
Is it better to finance CPO through GM Financial or my own bank?
It depends on which offer is actually cheaper after all fees and term adjustments. GM Financial often has CPO-specific rate programs a general bank loan can't match, but a credit union may still beat them for a strong-credit buyer. The practical move is to apply through the dealer and compare the result against your outside pre-approval.
Does North Carolina tax a CPO vehicle differently than a new one?
No. North Carolina applies the same vehicle titling tax to new and used vehicle titlings, including CPO units. There is no separate CPO tax category. The tax is calculated on the purchase price minus any trade-in allowance and is collected by the NC DMV when the vehicle is titled.
Can I include extended coverage or GAP in a CPO loan?
Yes. Extended service contracts, GAP coverage, and tire-and-wheel protection can typically be rolled into a GMC CPO loan at origination, which means they're financed over the loan term rather than paid up front. The trade-off is interest on those add-ons. Decide whether each product earns its cost before signing, not after.
Where Monroe buyers can go next
GMC CPO financing rewards buyers who prepare: know your credit tier, understand the mileage and age caps, and compare the CPO rate program against outside pre-approvals before signing. Done right, it's one of the stronger value plays in the used market — factory warranty coverage, inspected mechanicals, and rate access closer to new-vehicle tiers than standard used loans.
Readers in Monroe, NC who want this handled professionally can reach Griffin Buick GMC at (704) 288-0210 or griffinmonroe.com to review current CPO inventory, run a credit application, and compare GM Financial programs against outside offers. The dealership is located at 2500 West Roosevelt Boulevard in Monroe.