
How to Improve Your Credit Score for Auto Loan Approval in Monroe, NC
A practical 2026 guide to improving your credit score for a car loan in Monroe, NC — actionable steps, timelines, and what local lenders look for.
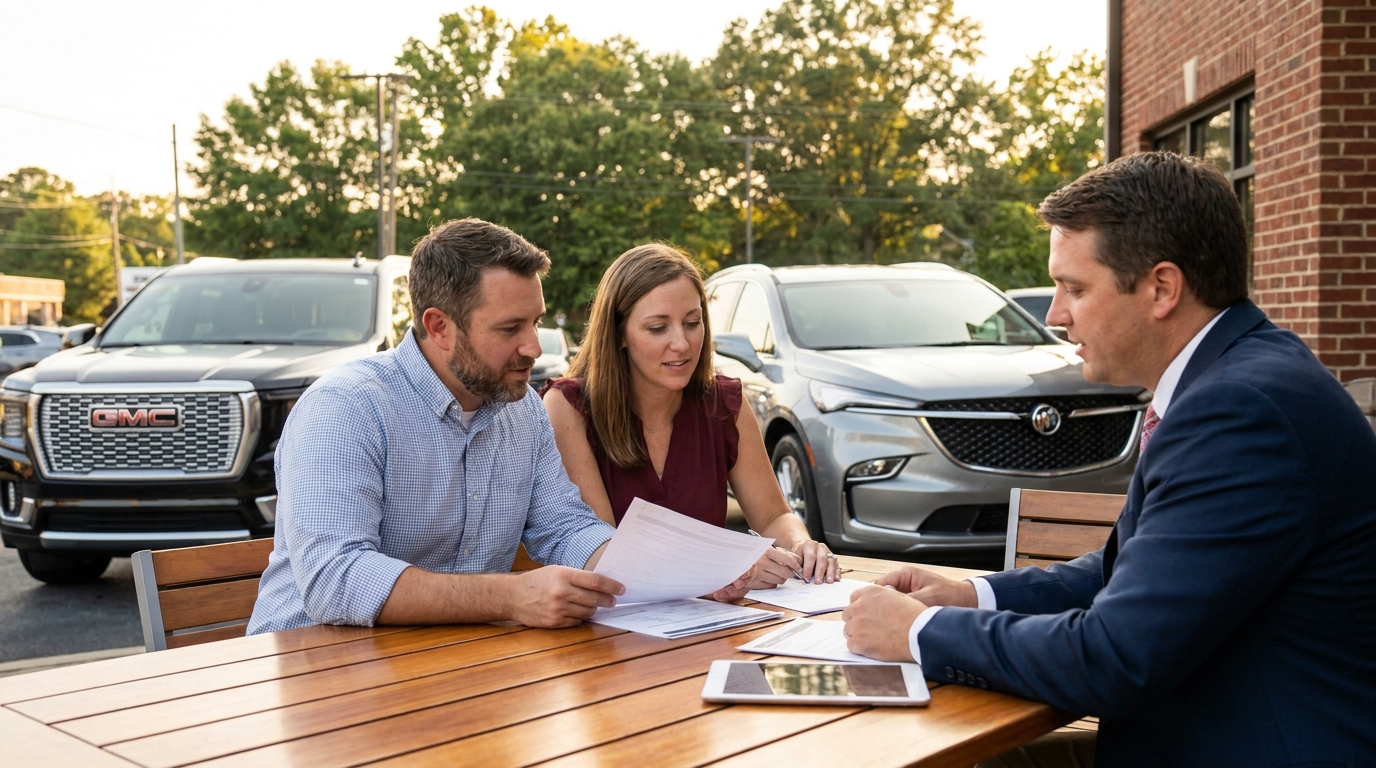
If you're shopping for a vehicle in Monroe, NC and your credit score is holding you back, you're far from alone. Union County buyers regularly walk into dealerships hoping to drive home in a new GMC Sierra or a certified pre-owned Buick Encore, only to discover that their credit score is the single biggest factor in what interest rate they'll qualify for — sometimes the difference between an affordable monthly payment and one that strains the household budget.
The good news: credit scores are not fixed. With a focused 60-to-120-day plan, most buyers can move their score meaningfully before they sign loan paperwork. Here's how to boost your credit for an auto loan, what lenders serving the Charlotte metro area actually look at, and how to time your improvements so you walk into the F&I office with leverage.
Why Your Credit Score Matters So Much for Car Financing
Auto lenders use your FICO Auto Score (a variation of the standard FICO model weighted toward auto loan history) to set your interest rate, loan term options, and sometimes whether you need a co-signer. In the current 2026 lending environment, the gap between a lower-tier score and a prime score can mean paying significantly more over the life of a 60-month loan.
Lenders typically slot buyers into tiers ranging from deep subprime at the low end to super prime at the high end, with each tier carrying different rate and term options. Moving up even one tier before you apply can meaningfully reduce your APR.
Step-by-Step: How to Improve Credit Score for a Car Loan
1. Pull Your Credit Reports First
Start by requesting free reports from all three bureaus (Equifax, Experian, TransUnion) at AnnualCreditReport.com. Reports can contain errors — a closed account showing open, a paid collection still listed as unpaid, or an account that isn't yours at all. Disputing inaccuracies is the fastest legitimate way to raise a score, sometimes within 30 days.
2. Pay Down Revolving Balances Aggressively
Credit utilization — how much of your available revolving credit you're using — is a significant factor in your FICO score. Lenders want to see utilization under 30%, and ideally under 10%. If you have a $5,000 credit limit, aim for a statement balance under $500 before applying for auto financing.
This is the single highest-leverage move for most Monroe buyers. Paying a credit card from high utilization down to under 10% can lift a score significantly in a single billing cycle.
3. Don't Close Old Accounts
Length of credit history matters. That dusty store card you've had since you moved to Union County a decade ago is probably helping your score more than you realize. Closing it shortens your average account age and reduces your total available credit (hurting utilization). Leave old accounts open, even if you don't use them.
4. Make Every Payment On Time, Every Time
Payment history is the largest single factor in your FICO score. Set up autopay for at least the minimum on every account. A single 30-day late payment can drop a good score substantially and stays on your report for years.
5. Avoid New Credit Inquiries Before Applying
Every hard inquiry trims a few points from your score. In the 90 days before you plan to finance a vehicle, don't open new credit cards, don't finance furniture, and don't let retailers run your credit at checkout. When you do shop for an auto loan, multiple dealer or lender inquiries within a short rate-shopping window can count as a single inquiry under FICO's auto-loan rate-shopping rules.
6. Consider Becoming an Authorized User
If a family member has a credit card with a long history and low utilization, being added as an authorized user can inherit that positive history onto your report. This is a legitimate, well-known tactic that works particularly well for younger Monroe buyers building credit for their first vehicle purchase.
How Long Does Credit Improvement Take Before Buying a Car?
Timing matters. Here's a realistic schedule:
- 30 days out: Disputed errors resolved, utilization paydowns reflected on the next statement cycle.
- 60–90 days out: Multiple billing cycles of low utilization and on-time payments compound into a meaningful score lift.
- 6 months out: If you're rebuilding from a major derogatory event (collection, repossession, bankruptcy discharge), this is the minimum window to see substantial movement.
For most buyers in the Monroe and Indian Trail area, a focused 90-day plan ahead of vehicle shopping produces the best return on effort.
North Carolina-Specific Considerations
A few details that matter for buyers financing in Monroe specifically:
- Highway use tax: North Carolina charges a Highway Use Tax on vehicle purchases instead of standard sales tax. This is collected at titling through the NCDMV and is typically rolled into your financed amount — meaning a higher credit tier saves you interest on this charge too.
- Trade-in credit: North Carolina applies the Highway Use Tax to the difference between your new vehicle price and your trade-in value, which reduces the taxable amount when you trade in your current car.
- Title and registration: Plan for NCDMV title fees and registration when budgeting. These costs are fixed regardless of credit, but a stronger score means more of your monthly payment goes to principal rather than interest.
What Lenders Look at Beyond the Score
Credit improvement car financing isn't only about the number. Lenders also evaluate:
- Debt-to-income ratio: Most auto lenders want your total monthly debt obligations (including the new car payment) under 40–45% of gross monthly income.
- Payment-to-income ratio: The car payment alone ideally stays under 15–20% of gross monthly income.
- Down payment: Putting 10–20% down signals commitment and reduces lender risk, often unlocking a better rate even at the same score.
- Employment stability: Two years at the same employer (or in the same field) strengthens your file significantly.
FAQ: Better Credit for a Car Loan
Can I get a car loan with a 580 credit score?
Yes, but expect a higher APR and possibly a larger down payment requirement. Many dealerships, including Griffin Buick GMC, work with subprime lenders for buyers in this range. Improving to 620+ before applying usually pays for itself within the first year of the loan through interest savings.
Does pre-qualifying for an auto loan hurt my credit?
Pre-qualification typically uses a soft pull and does not affect your score. The hard inquiry happens when you formally apply. Within a short rate-shopping window, multiple hard inquiries for auto loans can count as one.
Should I pay off my credit cards completely before applying?
You don't need a zero balance — you need low utilization on the statement date before you apply. Very low utilization — rather than a zero balance — can score well in most models.
How much will a co-signer help?
A co-signer with strong credit can move you into a better lending tier and lower your APR substantially. The co-signer is legally responsible for the loan, so it's a decision both parties should weigh carefully.
Will checking my own credit score hurt it?
No. When you check your own credit report or score, it generates a soft inquiry, which has no effect on your FICO score. Only hard inquiries — triggered when a lender formally pulls your credit — can cause a small, temporary dip. Monitoring your own credit regularly is a smart habit, especially in the months before you plan to finance a vehicle.
Is it worth waiting to improve my credit, or should I just buy now and refinance later?
Both paths can work, but the math usually favors waiting. Even a 60-to-90-day improvement window often produces enough score movement to drop you into a better lending tier, saving meaningful money over the loan term. Refinancing later is possible, but it requires another hard inquiry and a new application process. Contact Griffin Buick GMC to talk through your current situation before deciding.
Putting It All Together in Monroe
Improving your credit before financing a vehicle is one of the highest-return financial moves you can make — often worth more than negotiating hard on the sticker price. A 90-day plan focused on utilization, on-time payments, and clean credit reports puts most buyers in a meaningfully better lending tier by the time they're ready to shop.
When you're ready to look at vehicles or want a no-pressure conversation about financing options for your credit situation, the team at Griffin Buick GMC in Monroe, NC works with a range of lenders and can help you understand where you stand before you commit. Contact Griffin Buick GMC at (704) 288-0210 or visit griffinmonroe.com to browse inventory or schedule a financing consultation. Their 4.6★ rating across more than 1,300 Google reviews (as of May 2026) reflects a finance and sales process that buyers in Union County have come to rely on. One customer wrote: "Michael the financial person was also polite and easy to talk with" — exactly the kind of experience you want when working through credit questions before signing.
"