
How Buick Financing Works in Monroe, NC: A Clear Guide
Understand how GM Financial tiers, credit scoring, and dealer reserve shape your Buick loan in Monroe, NC — and what to do before you sign.
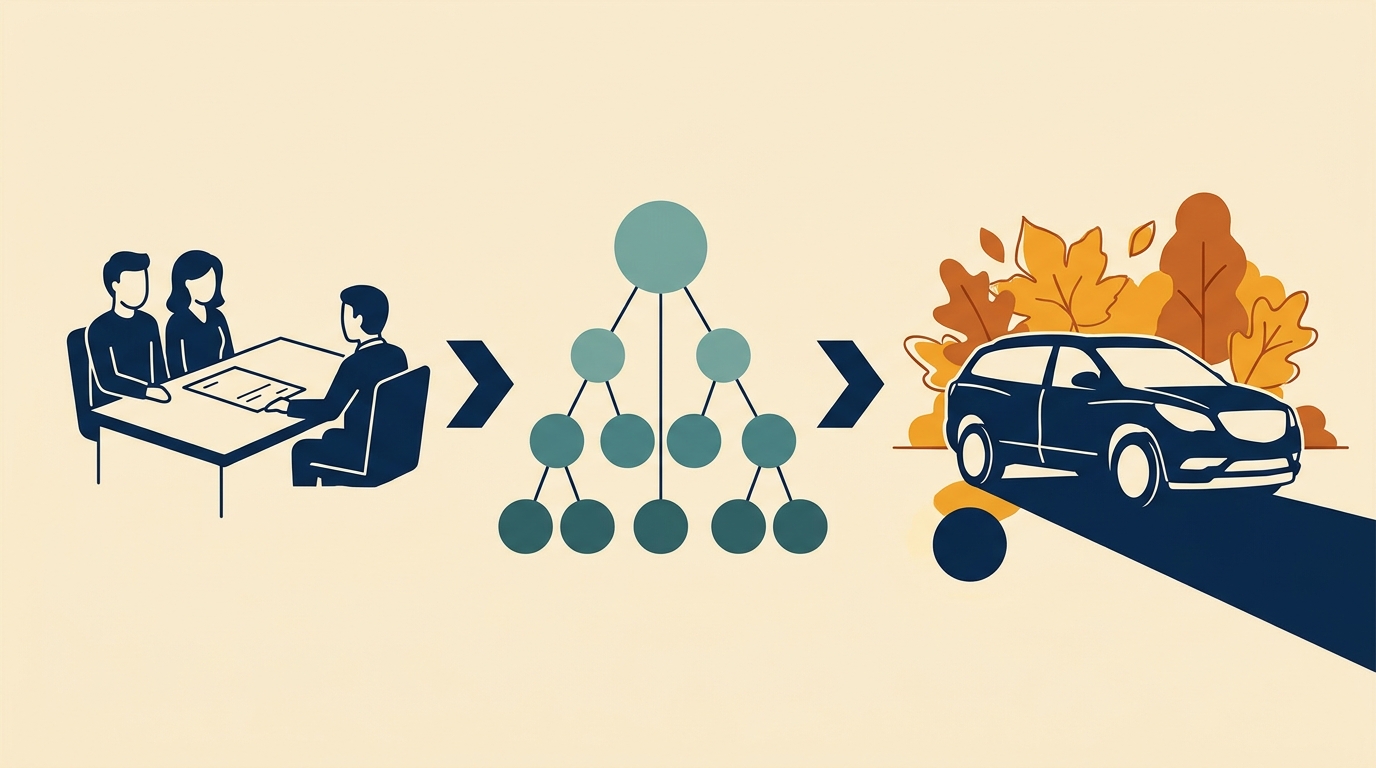
Buick financing in Monroe, NC works through an indirect lending model: you apply at the dealership, the dealership submits your application to GM Financial (Buick's captive lender) and often a network of other banks and credit unions, and the lender that approves you buys the retail installment contract from the dealer. Your APR is set by the credit tier you land in — prime or nonprime at GM Financial — plus any dealer markup (called dealer reserve) added on top of the lender's buy rate.
That's the mechanism. The rest of this guide explains how each piece actually works, what you can control, and how to compare a Buick financing offer in Monroe against outside benchmarks before you sign.
Who actually funds your Buick loan in Monroe, NC?
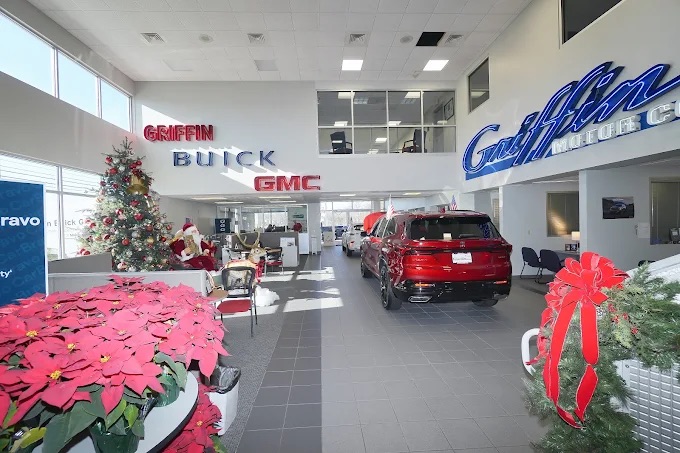
In almost every case, the dealership does not lend you the money — a third-party lender does, and the dealership sells your contract to them at closing. GM Financial is the captive option for Buick buyers, and its primary source of business is purchasing retail installment contracts from auto dealerships. Griffin Buick GMC, located at 2500 West Roosevelt Boulevard in Monroe, works with GM Financial and a network of lending partners when arranging financing.
GM Financial offers both prime and nonprime financing to GM dealers, meaning a single application at a GM dealership can be shopped across multiple lenders simultaneously. For a Buick shopper in Union County, that means a single application at a GM dealership can be shopped across multiple lenders simultaneously.
How does GM Financial decide your credit tier?
GM Financial places you in a prime or nonprime tier based on proprietary underwriting that weighs credit history, debt-to-income, and payment track record — the tier then drives your APR. GM Financial does not publish score cutoffs; approval and rate are decided internally, and the higher your profile, the better the terms.
Per GM Financial's guidance, credit tier placement weighs payment history, debt-to-income ratio, and credit depth, among other underwriting factors. Promotional APRs — the headline numbers you see in Buick ads — are reserved for "well-qualified" buyers and are not guaranteed to every applicant. Those promotions are also time-limited; what's available the week you shop depends on the active GM incentive calendar.
What is dealer reserve, and how does it affect your rate?
Dealer reserve is the spread between the "buy rate" GM Financial quotes the dealership and the "contract rate" you actually sign. If GM Financial approves you at 7.9% and the contract is written at 8.4%, the 0.5-point difference is dealer compensation — paid by the lender to the dealership as part of buying your contract. It is not disclosed as a separate line item on your retail installment contract.
Dealer reserve is legal and common across the industry; it's one of the ways a dealership gets paid for arranging financing. The practical implication for a Monroe buyer: your contract APR is negotiable in the same way the price of the vehicle is negotiable. If you walk in with a competing preapproval, the dealer has a reason to minimize the markup to win your business.
What North Carolina rules apply to a Buick retail installment contract?
North Carolina motor-vehicle installment sales are governed by the Motor Vehicle Retail Installment Sales Act under N.C. Gen. Stat. Chapter 25A, and the NC Office of the Commissioner of Banks oversees lenders operating under the state's Consumer Finance Act. Your contract must disclose APR, total finance charge, total of payments, term, and other required federal and state terms before you sign.
North Carolina does not cap dealer reserve as a disclosed line item, and GM Financial's buy rate is not something you'll see printed on your paperwork. What you can see — and should read carefully — is the APR, the amount financed, the schedule of payments, and any add-ons (service contracts, GAP, tire-and-wheel coverage) that have been folded into the amount financed.
How should Monroe buyers compare a GM Financial offer against outside lenders?
Get at least one independent preapproval from a credit union or bank before you sit down in the finance office, then compare it against the GM Financial contract offer side by side at the same term length. If the dealer's offer beats your outside preapproval, take it; if it doesn't, use the preapproval or ask the dealer to match. Credit union preapprovals are typically only usable at a dealership — Navy Federal Credit Union, for example, states its auto loan preapprovals cannot be used for private-seller purchases.
Those figures are benchmarks for comparison only — they are not Monroe Buick financing rates — but they give you a yardstick for whether a dealer offer is competitive. Those figures are benchmarks for comparison only — they are not Monroe Buick financing rates — but they give you a yardstick for whether a dealer offer is competitive.
What should you have ready before you apply?
Walk in with the pieces an underwriter will ask for and the comparison numbers you'll need in the finance office. Doing this before you choose a vehicle keeps the paperwork moving and makes it easier to spot a weak offer.
- Proof of income (recent pay stubs or tax returns if self-employed)
- Proof of residence in Monroe or the surrounding Union County area
- A valid driver's license
- Written out-the-door pricing on the Buick you want, including taxes, title, registration, and documentation fees
- At least one outside preapproval (credit union or bank) at the same loan term you plan to finance
- A clear number for your trade-in, ideally with a written offer from a third party as a floor
How do Buick model prices affect your financing math in 2026?
The vehicle you choose drives the loan amount, which drives the monthly payment at any given APR and term. Reference MSRPs give you a starting point for budgeting before taxes, fees, and any dealer discount or incentive.
| Model | Starting MSRP (as of Oct 2026) |
|---|---|
| Entry Buick SUV | the 2026 Buick Envista, starting at $24,700 (as of October 2026) |
| Compact Buick SUV | the 2026 Buick Encore GX, starting at $26,895 (as of October 2026) |
| Midsize Buick SUV | the 2026 Buick Envision, starting at $41,300 (as of October 2026) |
| Three-row Buick SUV | the 2026 Buick Enclave, starting at $46,400 (as of October 2026) |
| Top three-row Buick trim | the 2026 Buick Enclave Avenir, starting at $60,000 (as of October 2026) |
Those are manufacturer starting prices, not Monroe transaction prices, and they do not include destination charges, taxes, title, registration, or dealer fees. Griffin Buick GMC publishes current inventory and can provide a written out-the-door quote for any trim you're considering.
What does a Monroe Buick financing experience actually look like?
Buyers who have gone through the process at Griffin Buick GMC describe it in their own words better than any explainer can.
My wife and I just finished purchasing and receiving a new vehicle from Griffin Buick GMC Buick located in Monroe, NC. It was the most pleasant vehicle purchase I have ever experienced. The staff at Griffin are true professionals, no pressure at all. Mike M. helped us with the finances and Chandler B provided help with the sale. Both Mike and Chandler demonstrated exceptional and detailed knowledge of all aspects of finances and vehicle operations and use. Everyone we met was very friendly and professional and were very responsive and respectful to my wife and me. I sincerely thank Pete, Josh, Mike and Chandler for executing the sale, prepping the vehicle and providing training on functionality and technologies of the vehicle. All while displaying true professionalism and a real desire to help us. It was such a positive experience for us. If you want a great and positive car buying experience, you owe it to yourself to check out Griffin GMC Buick, located at 2500 Roosevelt Blvd in Monroe, NC. We will be back.
Frequently asked questions
Does Buick financing in Monroe, NC always go through GM Financial?
No. GM Financial is the captive lender and is almost always one of the lenders a Buick dealership submits your application to, but it is not the only one. Griffin Buick GMC works with GM Financial and a network of lending partners, which means your application can be shopped across multiple banks and credit unions in a single visit to find the best approval terms.
Can I use my own credit union loan at a Monroe Buick dealership?
Yes, as long as the preapproval is set up for dealership use. Most credit union auto loan preapprovals are set up for dealership use and may not be accepted for private-party purchases. Bring the preapproval paperwork with you and present it alongside the GM Financial offer so you can take whichever rate and term is better.
Why would my APR be higher than the advertised Buick rate?
Advertised promotional APRs are reserved for "well-qualified" buyers and depend on your credit tier placement by GM Financial, which weighs payment history, debt-to-income, and credit depth. If your profile doesn't hit the top tier, you'll be offered a higher rate. Dealer reserve — the markup added to the lender's buy rate — can also widen the gap between advertised and contract APRs.
Is dealer reserve the same as a dealer fee?
No. A dealer fee (like a documentation fee) is a line item disclosed on your contract. Dealer reserve is the spread between the lender's buy rate and your contract rate, paid by the lender to the dealership as compensation for arranging the loan. It isn't broken out as a separate charge, but you can effectively negotiate it by bringing a competing preapproval that forces the contract rate down.
What credit score do I need to finance a Buick in North Carolina?
GM Financial does not publish score cutoffs — approval is based on proprietary underwriting that considers payment history, debt-to-income, and in some cases two years of credit history. GM Financial offers both prime and nonprime tiers, so buyers across a wide credit range can usually find an approval; the score mostly determines the APR you qualify for, not whether you're approved at all.
Are Buick promotional APRs available all year in Monroe?
No. Promotional APRs from GM Financial are time-limited and tied to the active incentive calendar at the time of purchase, so what's available in one month may not be the next. They are also sometimes mutually exclusive with cash rebates, meaning you may have to choose between a low APR and customer cash. Confirm current offers in writing with the dealership before relying on any advertised figure.
The bottom line
Buick financing in Monroe, NC is a two-track process: the dealership arranges the loan through GM Financial and other partners, and your APR is the sum of the lender's underwriting decision plus any dealer reserve added on top. The buyers who end up with the best terms are the ones who walk in with a credit union preapproval in hand, written out-the-door pricing, and a clear understanding that the contract APR is negotiable. Readers in Monroe who want this handled professionally can reach Griffin Buick GMC at (704) 288-0210 or https://www.griffinmonroe.com/ to start the conversation.