
How Dealer Financing Rates Are Set in Monroe, NC
A data-backed look at what moves auto loan APRs at Monroe, NC dealerships — credit, term, vehicle, lender rules — with 2026 benchmarks and buyer tips.
Auto financing rates at Monroe, NC dealerships are set by a lender's underwriting decision — not by the dealership itself — and the number you see on the finance-office screen reflects your credit profile, the vehicle, the loan amount and term, and the lender's own cost of funds, plus any dealer compensation permitted by the lender's agreement. In Q3 2026, the average APR on a financed new vehicle in the U.S. was 7.0%, while used-vehicle financing averaged 10.6%, according to Edmunds data reported by beforeyoubuyx.com. Where your offer lands inside — or outside — that gap is what this article explains.
What actually determines a dealership auto loan rate?
A dealership auto loan rate is built from four inputs: the lender's base cost of capital, your credit risk profile (score, income, debt load, down payment), the collateral (vehicle year, mileage, value, loan-to-value), and the loan structure (term and amount financed). The dealer submits your application to one or more lenders, each returns a buy rate, and the finance office presents a contract rate that may include dealer compensation on top.
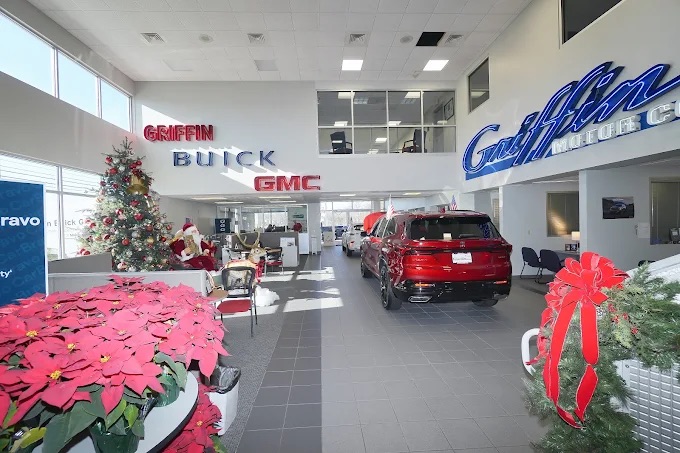
That final layer is the piece most buyers don't see. The lender approves a rate it is willing to fund; the dealer, within the lender's rules, may present a slightly higher APR, with the difference becoming compensation for arranging the loan. It's legal and disclosed in the contract — but it means the APR quoted at the desk is not automatically the lowest rate for which you qualify. Griffin Buick GMC works with GM Financial and a network of lending partners, which is the structure most franchise dealerships use to generate multiple competing offers on a single application.
How much do credit tiers move the rate in 2026?
Credit tiers move auto loan APRs dramatically. LendingTree's platform showed new-vehicle loan APR ranges of 5.34%–21.50% across credit-score bands in Q3 2026, and used-vehicle APR ranges of 8.41%–23.02% across the same bands. In other words, two Monroe buyers walking into the same showroom on the same day can be quoted rates nearly 16 percentage points apart on an identical vehicle.
Those ranges, per LendingTree, cover loan offers of at least $5,000 with terms of 48–72 months. For context, the Federal Reserve's commercial-bank series (as relayed by Morningstar) reported new-auto loan rates of 7.47% for 48-month terms and 7.54% for 60-month terms in August 2026 — a tighter, bank-only snapshot that excludes captive finance arms and subprime lenders. The spread between the bank average and the platform's upper band is almost entirely a credit-risk story.
Benchmark snapshot
| Benchmark | Rate | What it measures |
|---|---|---|
| U.S. new-vehicle avg APR, Q3 2026 | 7.0% | Edmunds, via beforeyoubuyx.com |
| U.S. used-vehicle avg APR, Q3 2026 | 10.6% | Edmunds, via beforeyoubuyx.com |
| Commercial banks, 48-month new auto | 7.47% | Federal Reserve series, Aug 2026, via Morningstar |
| Commercial banks, 60-month new auto | 7.54% | Federal Reserve series, Aug 2026, via Morningstar |
| LendingTree new-vehicle range, Q3 2026 | 5.34%–21.50% | Across credit-score bands, per LendingTree |
| LendingTree used-vehicle range, Q3 2026 | 8.41%–23.02% | Across credit-score bands, per LendingTree |
Why does the vehicle itself change the APR?
The vehicle changes the APR because lenders price risk against the collateral. A new vehicle with a predictable depreciation curve and a strong resale market gets a lower rate than a high-mileage used vehicle whose value could drop below the loan balance. That is the single biggest reason the national new-used APR gap was 3.6 percentage points in Q3 2026 (7.0% vs. 10.6%, per Edmunds).
Model year, mileage, loan-to-value ratio, and whether the vehicle is a captive brand (financed through the manufacturer's own lender) all shift the pricing. A Monroe buyer financing the 2026 GMC Terrain, starting at $30,200 (as of October 2026) through GM Financial is working with a captive lender whose rate card is tied to GMC's incentive strategy. Compare that to a buyer financing a seven-year-old import through an outside bank, and the APR gap is baked in before credit is even considered.
How do term length and amount financed interact with the rate?
Longer terms generally carry higher APRs and dramatically higher total interest, even when the monthly payment looks friendlier. In Q3 2026 the average term on a financed new vehicle in the U.S. was 70.5 months and the average amount financed was $44,664, per Edmunds data reported by beforeyoubuyx.com. For used, the average term was 70.4 months and the average amount financed was $30,703, per the same source.
Those averages matter because stretching a loan to 72 or 84 months to hit a target payment can push a buyer into negative equity — owing more than the vehicle is worth — for most of the loan. When you compare offers, compare APR, term, amount financed, fees, and total of payments. A lower monthly payment at a longer term is often a worse deal.
How do promotional and manufacturer rates fit in?
Manufacturer-sponsored promotional financing is a separate product from a standard market-rate loan. These offers are typically limited by model, term, buyer credit tier, and geography, and they are often presented as an alternative to another incentive — meaning you may have to choose between a low promotional APR and a cash rebate on the same vehicle. The math is not always in favor of the promotional rate; on a smaller loan, the rebate can beat the interest savings.
Because specific current promotions change frequently and depend on model, term and qualification, Monroe buyers should confirm current offers directly with Griffin Buick GMC rather than relying on general benchmarks. The dealership carries new Buick and GMC vehicles as well as CarBravo certified pre-owned vehicles, including models from other major manufacturers, each of which can carry different financing paths.
What local Monroe, NC factors affect a dealership loan?
Monroe sits in Union County within the Charlotte metro commuting orbit, which shapes the kinds of vehicles — and loan sizes — buyers typically finance. Pickups and SUVs for I-485 and US-74 commuting, three-row family vehicles, and work trucks are common, and loan-to-value underwriting responds to those vehicle choices. Weather is also background context: the North Carolina State Climate Office noted Monroe experienced 22 consecutive dry days at the start of September 2026 during an unusually warm, dry statewide month, which affects showroom traffic but not APRs directly.
North Carolina lending rules, dealer licensing, and credit-sale requirements apply to any auto loan originated in Monroe. Because those rules change and vary by transaction type, Monroe buyers should confirm the specific disclosures on their own contract rather than rely on national generalizations.
How can a Monroe buyer actually lower the rate?
Four moves consistently move the needle. First, pull your credit report and resolve errors before applying — the band you fall into on the LendingTree 5.34%–21.50% new-vehicle spread is the single biggest lever. Second, get a preapproval from your bank or credit union before you walk in, so the dealership's finance office has to beat a real number, not an abstraction. Third, bring a meaningful down payment; a lower loan-to-value ratio reduces the lender's risk and often the rate. Fourth, choose the shortest term you can comfortably afford.
A buyer who shared their experience at Griffin Buick GMC described the finance process this way:
My wife and I just finished purchasing and receiving a new vehicle from Griffin Buick GMC Buick located in Monroe, NC. It was the most pleasant vehicle purchase I have ever experienced. The staff at Griffin are true professionals, no pressure at all. Mike M. helped us with the finances and Chandler B provided help with the sale. Both Mike and Chandler demonstrated exceptional and detailed knowledge of all aspects of finances and vehicle operations and use. Everyone we met was very friendly and professional and were very responsive and respectful to my wife and me. I sincerely thank Pete, Josh, Mike and Chandler for executing the sale, prepping the vehicle and providing training on functionality and technologies of the vehicle. All while displaying true professionalism and a real desire to help us. It was such a positive experience for us. If you want a great and positive car buying experience, you owe it to yourself to check out Griffin GMC Buick, located at 2500 Roosevelt Blvd in Monroe, NC. We will be back.
That kind of walkthrough — being told what the APR, term and total of payments actually mean — is the right standard to hold any finance office to.
Frequently asked questions
Can a Monroe dealership mark up the lender's rate?
Yes. Within the lender's agreement, a dealership may present a contract APR higher than the lender's buy rate, with the difference serving as dealer compensation for arranging the loan. The practice is legal and disclosed in the loan documents, but it means the quoted rate isn't necessarily the lowest rate you qualify for. Asking directly, and comparing against an outside preapproval, is the simplest check.
Why is my used-car APR higher than a new-car APR?
Used vehicles carry more collateral risk — unpredictable condition, faster depreciation on older models, thinner resale markets — so lenders price them higher. In Q3 2026 the U.S. average APR on financed used vehicles was 10.6% versus 7.0% on new, per Edmunds data reported by beforeyoubuyx.com. Your individual rate depends on the vehicle's age, mileage, and loan-to-value, plus your credit profile.
Does a longer loan term always mean a higher APR?
Not always, but usually. Commercial-bank new-auto loan rates in August 2026 were 7.47% for 48-month terms and 7.54% for 60-month terms, per a Federal Reserve series relayed by Morningstar — a small spread. Captive and subprime lenders typically widen that gap more. Even when the APR difference is small, a longer term dramatically increases total interest paid.
Should I take the promotional APR or the cash rebate?
It depends on the loan size and the gap between the promotional APR and the market rate you'd otherwise qualify for. On smaller loans or shorter terms, the rebate often wins; on larger loans at longer terms, the promotional APR can save more. Run both scenarios through a total-of-payments calculation before deciding, and ask the finance office to show you both quotes in writing.
How does a preapproval change the dealership conversation?
A preapproval from your bank or credit union sets a floor. The dealership's finance office now has to match or beat a specific APR and term to earn the loan, rather than quoting into a vacuum. It also separates the vehicle price negotiation from the financing negotiation, so the dealer can't shift margin between the two to make a payment look better than it is.
What should I compare across loan offers?
Compare APR, term in months, amount financed, itemized fees, and total of payments — not the monthly payment alone. A lower monthly payment stretched over 84 months at a higher APR usually costs thousands more than a shorter loan at a modestly higher payment. Also confirm whether the APR is a promotional rate tied to a specific model or buyer qualification.
Working with Griffin Buick GMC on financing
Rate shopping is useful, but understanding what drives the rate is what actually changes the offer you receive. Monroe, NC buyers who want to walk through credit tier, term, vehicle selection, and the tradeoff between promotional APR and other incentives can reach Griffin Buick GMC at (704) 288-0210 or https://www.griffinmonroe.com/ to get a written quote and compare it against any outside preapproval.